Can You Prove It? How the ROAD to Housing Act Institutional Investor Ban Changes Single-Family Rentals
Get a summary of this article with your favorite AI

AI Summary
- •Under the ROAD to Housing Act institutional investor ban, a large institutional investor (one with investment control over 350 or more single-family homes) generally can't buy another home, or even sign a contract to buy one, from January 7, 2027 unless the purchase is an excepted purchase (Treasury).
- •Treasury's proposed rule turns each exception into something you have to prove: dates, inspections, spend thresholds, written programs and renter records.
- •That proof usually lives in scattered files and inboxes, which is where most teams will feel the squeeze.
- •A readiness scorecard and a single-family rental compliance checklist are below. Public comments on the proposal are due November 23, 2026.
If your plan for next year is “buy more homes,” there’s a date worth circling: January 7, 2027.
That’s when the ROAD to Housing Act institutional investor ban kicks in, and it swaps the question “does this deal pencil?” for “can you prove this deal is allowed?” For anyone running 350 or more single-family homes, that means dates, inspections and renter paperwork have to be in order before you sign.
Below: what you’d actually have to show, what the tests cost in real dollars, and a quick way to see where your own operation stands.
Why does the ROAD to Housing Act institutional investor ban change how you run a single-family rental business?
Because "buy more homes" stops being a plan you can run on autopilot. Under the institutional investor ban, once you control 350 or more single-family homes, every new purchase has to fit a named exception, and you're the one who has to prove it (Treasury).
Who counts as a large institutional investor? A for-profit entity in the business of investing in, owning, renting, managing or holding single-family homes that has direct or indirect investment control over at least 350 of them, alone or with others (SBA Office of Advocacy).
Now picture a seller sending over a 40-home package. The old question was "does the yield work?" The new ones sound more like this:
- Were any of these homes ever owner-occupied?
- How old are the certificates of occupancy?
- Can you pull that paperwork this afternoon, before anyone signs?
That last part matters. The prohibition covers entering into a contract to buy, not just closing.
The 350 count isn't just what sits on your balance sheet. Joint ventures and fund positions can move you across the line, because the test is control, not title.
Treasury's proposal also says a minority investor counts as passive only if it shares no directors or officers with the owner and holds no "property control right," meaning any consent, approval or veto over buying, selling, holding, leasing, renovating or managing the homes (proposed rule).
That’s also why growth planning turns into a modeling exercise. Deciding whether the next dollar goes into a build-to-rent project, a rehab pipeline or the homes you already own means comparing returns and risk side by side. That’s a key part of underwriting single-family rental deals, especially when acquisition plans also need to account for the Act’s restrictions.
What Would You Actually Have to Prove for An Excepted Purchase?
For each exception, Treasury's proposed rule comes down to a short list of facts you can put on paper. The statute calls these "excepted purchases." Here's the cheat sheet, and since these are proposals, details can still change.
| Exception | What you'd need to show | Records that back it up |
|---|---|---|
Build-to-rent exception | Home never owner-occupied before you bought it, bought within 18 months of its certificate of occupancy, and first occupied by renters | Certificates of occupancy or construction records, proof of no prior owner-occupancy, leasing records showing a renter moved in first |
Renovate-to-rent exception | Home failed the structural or core-system parts of local building code when you bought it, you resolve all material deficiencies, and improvements total at least 15% of the structure's price (a safe harbor counts 10% spent on structural or core systems) | Inspection reports, code violation notices, permits, scopes of work, invoices, proof of payment, price calculations |
Homeownership program | Rent and fees no higher than similar homes, free positive rent reporting, meaningful financial support, and a right to buy at no more than fair market value minus that support | Lease terms, rent comparisons, payment history, support calculations |
Program to boost homeownership | Free positive rent reporting, a written notice plus 30-day first look, a right of first refusal, and meaningful financial support | Dated written notices, offer records, support documentation |
Other excepted purchases | Purchases tied to debts previously contracted, loss mitigation or servicing duties, or bought from another large institutional investor that owned the home on enactment day or bought it in compliance | The seller's acquisition history, loan and servicing documents |
Treasury spells out the records it expects for the first two rows. For the renter programs, the last column is the practical read of what the notice and payment requirements will demand.
One more piece: each program has to be real before you buy. Treasury defines a "program" as written policies or procedures adopted before the purchase and built so every purchase meets the rules. You can't decide afterward that a deal belonged to one.
Also worth knowing: Treasury says the build-to-rent exception doesn't stop you from selling those homes later.
Back to that 40-home package. The files that answer these questions (purchase agreement, rent roll, inspection reports, certificate-of-occupancy records) rarely sit in one place, which turns deal screening and due diligence into a scavenger hunt. Document-review tools can read them as a set and flag what's missing. Deal AI goes a step further and scores opportunities against criteria you define, so something like "CO within 18 months" can sit right next to yield as a pass/fail line. If you want to see how technology can help bring this review together, take a look at our guide to AI real estate deal analysis for single-family acquisitions.
Screen Deals Before You Sign
Document review and deal scoring that flag missing proof before a contract goes out.
What Do the Percentage Tests Actually Cost You in Dollars?
More than most people expect, because the renovate-to-rent exception is measured against the structure's price, not the full price. Treasury proposes defining that as the purchase price minus the tax-assessed value of the land (proposed rule).
Here's what that looks like with two made-up purchases (illustrative numbers, simple math from the proposal):
| Scenario (illustrative) | Purchase price | Tax-assessed land | Structure basis | 15% requirement | 10% structural/core safe harbor |
|---|---|---|---|---|---|
A | $300,000 | $60,000 | $240,000 | $36,000 | $24,000 |
B | $300,000 | $90,000 | $210,000 | $31,500 | $21,000 |
Same price, but the required spend drops by $4,500 in scenario B purely because the county assessed more of the value to land.
Two things to keep straight:
- The 10% safe harbor isn't a shortcut. It only covers the "substantial rehabilitation" piece. You still need total improvements of at least 15%.
- Assessments are messy. Treasury itself notes assessed values can be outdated, under appeal or unavailable at purchase, and it has asked for comment on alternatives such as appraisals.
Since the land-versus-structure split drives the test, you'll want clean comps and assessment data on every rehab candidate before you bid. That's the sort of comparable-sales and market-data legwork Valuation AI automates, and it ends in a valuation report you can drop straight into the deal file.
Renter support has its own math. Treasury's proposed safe harbor for "meaningful financial support" is the lesser of $5,000 or a percentage of the home's price: 2.5% for renters of at least five years, 3.5% for at least seven. The percentage applies to the lesser of the purchase price or the county's FHA one-unit loan limit.
In practice, the $5,000 cap does most of the work. At 2.5% it kicks in on any base above $200,000, and at 3.5% above roughly $142,857 (illustrative math from the proposed figures).
How Ready Are You Right Now, Honestly?
Score yourself on the ten questions below: 0 for no, 1 for partly, 2 for yes. It's a quick gut-check on where your single-family rental compliance stands, built from the wording in Treasury's proposed rule. Think of it as a rule of thumb rather than a regulatory standard.
| S.NO. | Question | Why it's on the list |
|---|---|---|
1 | Do you know your current count of homes under direct and indirect control, including joint ventures and fund positions? | Coverage turns on investment control, alone or with others |
2 | Are your rules for each exception written down before you buy? | A Treasury "program" has to exist before the purchase |
3 | Can you pull certificate-of-occupancy dates and proof of no prior owner-occupancy for build-to-rent buys? | Both are core build-to-rent facts |
4 | Do you capture an inspection or code-deficiency record at purchase for renovate-to-rent homes? | Deficiency is judged at the time of purchase |
5 | Do you record the tax-assessed land value at purchase? | It sets the structure basis for the 10% and 15% tests |
6 | Can you total improvement spend per home against those thresholds? | The tests apply home by home |
7 | Do you keep renter tenure and payment history in one place? | Support steps up with years rented, and positive rent reporting is required |
8 | Can you send and date-stamp written notices to renters? | First-look and right-of-first-refusal timing runs off notice dates |
9 | Do renters in a program know exactly who to ask about their rights and timelines? | Support and first-look terms are written into the contract |
10 | Do you know which co-investors share directors or officers with you, or hold approval or veto rights? | Passive-investor status depends on both |
How to read your total:
- 0 to 7: early days. Start with questions 1 and 2. They shape everything else.
- 8 to 14: partway there. Your gaps are probably paperwork and tracking, not strategy.
- 15 to 20: in solid shape. Keep an eye on the final rule, since details may shift.
If questions 7 and 8 made you wince, you're in good company. Platforms like Tenant AI keep profiles, lease milestones, payment history and communication logs in one place, which is the setup renter programs lean on. There's more on how that works in this guide to centralized resident records.
Keep Renter Records Ready
Put tenure, payment history and notices in one place your whole team can pull from.
What Happens to Leasing and Resident Calls Once These Programs Start?
You get more moving parts, more questions, and tighter clocks. A few places it shows up:
- Build-to-rent lease-up gets timed. A qualifying home has to be first occupied by renters, so the gap between certificate of occupancy and first lease is real money. Scattered addresses make tours harder to staff than a single leasing office. Instant replies, auto-booked tours and follow-up nudges are what shrink that gap, and they're exactly what Leasing AI automates for single-family and build-to-rent portfolios.
- Notices run on clocks. In Treasury's proposed safe harbor, a renter gets written notice before you list the home, then 30 days before you can market it or take other offers, then five business days to match a qualifying outside offer under the right of first refusal (proposed rule). A missed date is a missed requirement.
- Renters will have questions. When does my first-look window start? Is positive rent reporting turned on? How much support do I get? Some of those calls will land after the office closes, and Voice AI can pick up around the clock, capture the details and route anything urgent to the right person.
Who Else Gets Pulled into This?
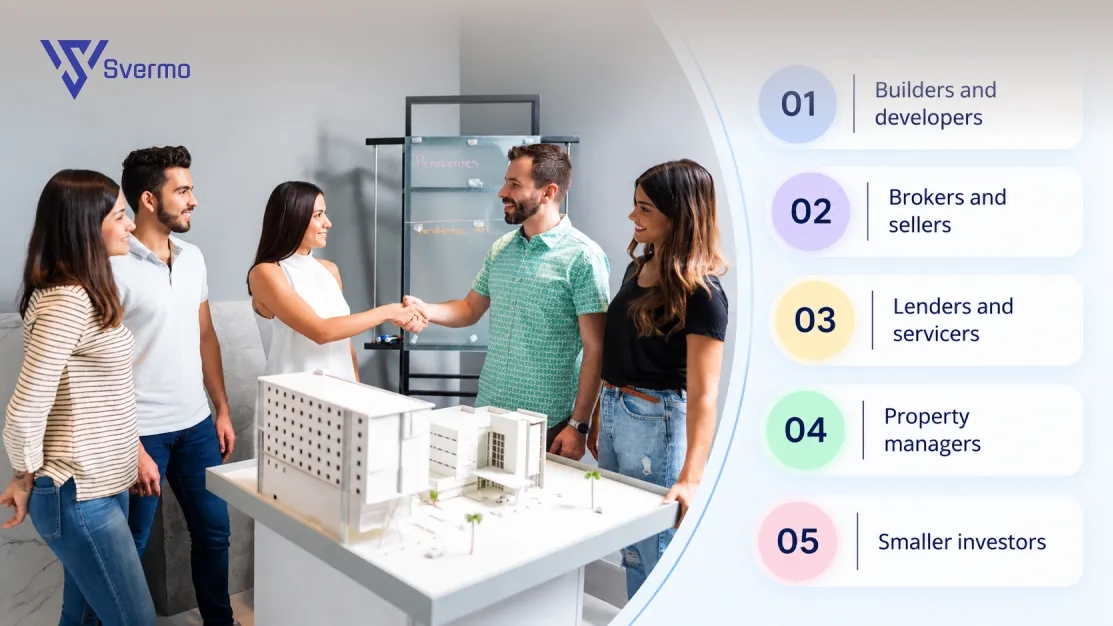
Anyone who builds for, sells to, lends to or manages homes for a large institutional investor. Here's how it plays out by role:
- Builders and developers: the build-to-rent exception hinges on buying within 18 months of the certificate of occupancy, so your buyer's timeline and your exit plan need to line up.
- Brokers and sellers: the pool of eligible institutional buyers narrows. Sales between large institutional investors are still allowed when the seller owned the home on enactment day or bought it in compliance.
- Lenders and servicers: a separate excepted-purchase category covers purchases by a servicer, lender or other party with a legal right to the home, made for loss mitigation or servicing duties after specified default events rather than as a long-term investment strategy.
- Property managers: Treasury reads "in the business of" broadly enough to include managing homes for fees, though coverage still depends on investment control over 350 homes. If you manage for covered owners, expect more requests for unit counts, occupancy history and resident records. Here's a closer look at AI for property management if that side of the work is new to you.
- Smaller investors: below 350 you're not covered, but remember the count includes control exercised together with others.
The SBA's Office of Advocacy has encouraged small homebuilders, renovators, property managers, lenders and smaller investors that work with large investors to tell Treasury how the definitions would affect them (SBA alert).
What Should You Do Before January 7, 2027?
Work through the list below in order. It doubles as a single-family rental compliance checklist, and each step ties back to something Treasury says it expects or asks for in the proposal.
- Count your homes. Map everything you control directly or indirectly, alone or with others. The test for a large institutional investor is investment control of at least 350 single-family homes (Treasury).
- Write your program down before the next purchase. The proposal calls for written policies or procedures adopted before you buy, built so every purchase meets the rules (proposed rule).
- Start collecting the paper trail Treasury lists. For build-to-rent, collect certificates of occupancy, proof of no prior owner-occupancy and leasing records. For renovate-to-rent, keep inspection reports, permits, invoices and proof of payment. A real estate due diligence checklist can help your team keep these records organized in the due diligence file for each home.
- Record the land-versus-structure split. Capture the purchase price and tax-assessed land value on every rehab candidate, since the 10% and 15% tests run off the structure's price.
- Set up dated written notices. The proposed first-look and right-of-first-refusal safe harbor runs on notice dates.
- Plan for HUD reporting. Large institutional investors owe HUD an annual notice about the homes under their control, and HUD will set the form and manner.
- Decide whether to comment by November 23, 2026. Submit through regulations.gov, and say so if you're a small business (SBA). Treasury posed dozens of specific questions on definitions, price calculations and records.
- Run it past counsel. This is the first phase. Treasury has said later rulemakings may cover compliance procedures, reporting, recordkeeping and enforcement.
So Where Does that Leave Single-Family Rental Investors and Acquisitions Heads?
The ROAD to Housing Act institutional investor ban narrows one path to growth, but mostly it raises the bar on proof. The teams that keep moving will be the ones who can answer "does this qualify, and where's the paperwork?" in an afternoon instead of a week.
Start with the count, write the program down, and get your records into one place. Single-family rental compliance gets a lot easier from there.
This article is general information, not legal advice. Treasury's rule is a proposal and may change before it's final.
Sources
- SBA Office of Advocacy: Treasury Proposes Rule to Implement the ROAD to Housing Act Ban on Large Institutional Investor Purchases of Single-Family Homes
- U.S. Department of the Treasury press release, October 22, 2026
- Treasury proposed rule: 21st Century ROAD to Housing Act Prohibition on Large Institutional Investor Purchases of Single-Family Homes (Federal Register pre-publication PDF)
- Submit comments on regulations.gov, docket TREAS-DO-2026-0529
 https://www.linkedin.com/in/saanvi-verma-38711a36a
FAQs
It's Section 1001 of the 21st Century ROAD to Housing Act, enacted July 11, 2026. It bars a large institutional investor from buying single-family homes unless the purchase is an excepted purchase, and it takes effect January 7, 2027 (proposed rule).
A for-profit entity in the business of investing in, owning, renting, managing or holding single-family homes that has direct or indirect investment control over at least 350 of them, alone or with others (Treasury, SBA).
The ban is written around purchases, and Treasury's proposal clarifies how purchases are treated rather than requiring sales. Edge cases are a question for counsel and the final text.
Up to the greater of $1 million or three times the purchase price of the property, land included. If one purchase involves more than one large institutional investor, Treasury proposes counting it as a single violation for the maximum penalty (proposed rule).
No. It's a proposal, and public comments are due November 23, 2026 (SBA). Treasury calls it the first phase of a phased approach.
Under the proposal, an investor that shares no directors or officers with the entity owning the homes and has no property control right over them (Treasury).
No. That's a legal call. What AI can do is help you gather and check the evidence: reading purchase documents, flagging missing records, scoring deals against criteria you set, and keeping resident records and call logs organized so proof is easy to produce.