AI Property Valuation for Residential Real Estate: Approaches, Data, Accuracy and Compliance (2026 Guide)
Get a summary of this article with your favorite AI

AI Summary
- •AI valuation gives every property a consistent first estimate, so human time goes to exceptions instead of manual research on each file.
- •Most tools use comparable-based, regression or machine learning methods, or a mix. Ask any vendor to explain theirs in plain terms.
- •Data quality sets the ceiling: current records, clean sales, and a visible list of what was fixed, dropped or missing.
- •No industry-wide accuracy figure exists. Back-test on your own closed sales, by market and property type.
- •A defensible value comes with a file: method, data, comparables, confidence, review record and testing.
AI property valuation for residential real estate gives valuation teams something they rarely have: a consistent first answer for every property, without ordering manual research each time. The hard part is not getting a number. It is getting a number you can explain to a lender, a client or an auditor.
Rules are catching up with that need: federal quality control standards for automated valuation models took effect on October 1, 2025, and bank model-risk guidance was replaced in April 2026. This blog covers how AI valuation works, the approaches and data behind it, how to test and defend a value, where compliance applies, and what to check before you choose a tool.
What is AI property valuation for residential real estate?
It is the use of AI and statistical models to estimate a home's value from its characteristics, comparable sales, market data and other inputs, usually with a value range and supporting evidence. Several names describe the same idea: AI real estate valuation, automated real estate valuation, automated property valuation and an AI home valuation tool.
An AI valuation for residential properties works the same way, with inputs tuned to homes. In most tools an automated valuation model (AVM) sits at the center, and an AVM real estate valuation is reviewed by a person before it is used.
What matters is what the output is for. A model estimate is not a licensed appraisal, and each valuation type fits different jobs:
| Type | Who produces it | Typical use | Defensibility |
|---|---|---|---|
AI valuation or AVM | Software, reviewed by a person | Screening, portfolio monitoring, pricing support, some lending evaluations | Depends on method, data, testing and documentation |
Evaluation | Regulated lender's process, which can use an AVM | Lending below the appraisal threshold | Must meet supervisory expectations |
Appraisal | Licensed appraiser | Transactions that require one | Highest, within appraisal standards |
Broker price opinion | Agent or broker | Pricing guidance | Regulators say it alone doesn't meet appraisal or evaluation standards |
How does AI property valuation work for residential real estate?
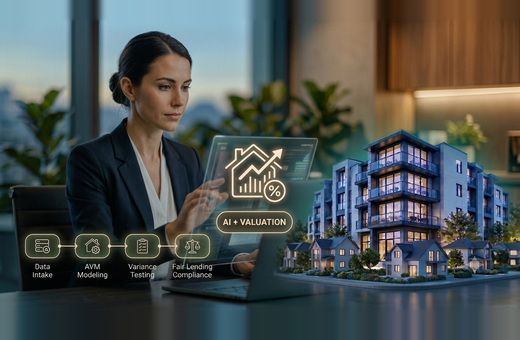
AI valuation follows a pipeline: gather property and market data, clean it, find comparable properties, estimate a value, rate its confidence and produce a report a person can review. The software does the repetitive steps; the reviewer decides whether the result is fit for the purpose.
- Collect: property records, sales history, listings and local market data.
- Clean: fix errors, fill gaps where possible and flag what can't be filled.
- Compare: select comparable sales and measure how similar they are.
- Estimate: apply the model to produce a value and a range.
- Score: indicate how reliable the estimate is, and why.
- Report: show the value, the evidence and the data gaps.
- Review: a person accepts, adjusts or escalates.
Here's what valuation managers often ask: "I manage property valuations across a large residential portfolio, and ordering manual research for every property takes too much time. How can AI help me generate defensible valuations without sacrificing the data quality and review process my team needs?"
Answer: let AI do the research and first estimate for every property, and spend human time on the exceptions. Set rules that decide which values pass automatically, which get a quick review and which go to full review, and keep the evidence attached to every value so a reviewer never starts from scratch.
What are the main approaches to AI property valuation for real estate?
Most AI valuation tools use one or a mix of three approaches: comparable-based, regression-based and machine learning models. The International Association of Assessing Officers' AVM standard describes comparable sales models, direct market models built with multiple regression, and artificial neural networks, along with cost and income approaches for some property types. That holds for any automated valuation model real estate lenders or brokers adopt.
| Approach | How it works | Strength | Watch for |
|---|---|---|---|
Comparable sales | Selects similar sales and adjusts for differences | Easy to explain to a reviewer | Depends on enough good comps nearby |
Regression (hedonic) | Estimates how each feature, such as size or location, affects price | Transparent about what drives value | Needs clean data and well-chosen variables |
Machine learning | Learns patterns across many sales, including non-linear ones | Can capture complex relationships | Can be harder to explain; the IAAO standard notes neural networks' limited explainability |
Hybrid or ensemble | Combines methods | Can offset one method's weak spots | Ask the vendor which methods and how they are weighted |
How does an automated valuation model calculate property value? An automated valuation model for real estate takes a property's characteristics, finds or learns how similar properties sold, adjusts for differences such as size, condition and timing, and outputs an estimate with a range. The calculation varies by model type, so ask a vendor to describe the method in plain terms. A vendor that can't is a warning sign.
The point is not to crown one approach. Machine learning real estate valuation can fit complex markets, while a comparable-based model is easier to show to a client. Many teams want both: a model that finds the value and a comparable view that shows why.
How does AI comparable sales analysis work in real estate?
AI comparable sales analysis in real estate finds recent sales of similar homes, scores how similar each one is to the subject property and adjusts for the differences. It is the same logic an analyst follows by hand, applied to every property with the same rules. AI comparable property analysis also tends to search more widely and more quickly than a person can on each file.
A sound comparable analysis does five things:
- Selects comparables on more than distance: size, age, style, lot, condition and neighborhood all count.
- Screens out bad sales: non-arm's-length transfers, foreclosure sales where they don't fit the purpose and obvious data errors.
- Adjusts for time: a sale from a rising or falling market needs a market-movement adjustment before it is comparable.
- Adjusts for differences: a bigger lot or an extra bathroom changes the value, and the adjustment should be visible.
- Weights by similarity: closer matches count more than loose ones.
The test for a reviewer is simple: can you open the comparables, see why each was chosen and see what was adjusted? If the tool shows only the final number, you can't check its reasoning, and neither can anyone you present it to.
What data does AI property valuation use for residential properties?
AI valuation draws on property records, sales transactions, listings, property characteristics, location data and market trends. Residential property valuation data analysis is only as good as these inputs, so data quality sets the ceiling on the result.
| Data type | Examples | Quality question |
|---|---|---|
Property records | Tax assessor data, lot size, year built, bedrooms | Is it current and complete? |
Sales data | Recorded sales, price, date, arm's-length or not | Are non-market sales excluded? |
Listings | Active and pending listings, price changes | Is it timely, and does it match recorded sales? |
Location | Neighborhood, schools, proximity, geography | Is it fine-grained enough? |
Market and economic data | Local price trends, rates, employment | How often does it update? |
Condition information | Renovations, repairs, photos or inspections, when available | Is it verified? |
The IAAO standard is specific about data. It says data integrity and availability shape the model, that data should be verified against its relationship to sale prices, that inconsistent or incomplete data shouldn't be used to build or calibrate a model, and that scraped data needs a quality-control plan and attention to terms of use.
Here's what teams with a lot of data ask: "We have access to large amounts of property and market data, but our team spends too much time cleaning, comparing, and interpreting it before producing a valuation. How can AI use this data to speed up residential property valuation while keeping the results reliable?"
Answer: let AI do the cleaning, matching and comparison, and require it to show what it fixed, what it dropped and what is still missing. Speed without that record is how bad data reaches a final value.
What factors should an AI property valuation model consider?
A sound model weighs the factors a buyer would: location, size, layout, age, condition, lot and features, plus when each comparable sold and how the market has moved since. Check that your tool handles these:
- Location: neighborhood and street-level effects, not only ZIP code.
- Physical characteristics: living area, rooms, lot, age and quality.
- Condition and updates: often the hardest factor to capture from records.
- Time: how recent each comparable sale is, and the market's direction since.
- Comparable fit: how similar each comparable truly is, not just how close.
- Uncertainty: whether the model flags when its inputs are thin.
How should AI property valuation handle unusual properties, thin comparables and changing markets?
It should lower its confidence, widen the range, say why and send the property to a person. A model should know when it doesn't know, and the system should act on that signal.
Here's the concern many teams raise: "I worry that an AI-generated property value could be inaccurate when market conditions change or when there are not enough comparable properties nearby. How should an AI valuation system handle unusual properties, limited comparable sales, and rapidly changing residential markets?"
Well, treat these as review triggers, not edge cases to hide. A good system should:
- Flag thin evidence: few recent comparable sales, large distances or big differences between comparables and the subject.
- Widen the range and lower confidence when evidence is thin.
- Escalate unusual properties to a person with the reasons attached.
- Watch for drift: the IAAO standard calls for updating models as markets change and using ratio studies to detect drift, and for periodic checks that the sample still represents the market.
Rapid market change is a model-health issue as much as a property issue, so monitor performance over time, not just at launch.
What are the limits of AI property valuation?
AI valuation is only as good as its data, its method and the market it was built for. It can miss what records don't show, and it can be confidently wrong when conditions shift. Knowing the limits is part of using it well.
- Condition and quality: interior condition, recent renovations or deferred maintenance often aren't in records, so the model may miss them.
- Unique properties: custom homes, unusual layouts and very small markets have few comparables.
- Stale or wrong data: an error in a property record flows into the value.
- Market turns: models trained on past sales can lag a sudden change.
- Overconfidence: a precise-looking number can hide a wide real range.
- Bias in data: historical patterns can carry unfair differences into the output, which is why nondiscrimination testing matters.
None of this means AI valuation can't be used. It means the review rules, confidence indicators and testing described above are not optional extras.
How accurate is AI property valuation for residential real estate?
AI property valuation accuracy varies by property type, market, data and use, and there is no single industry-wide figure. Judge any tool by testing it on your own closed sales, using metrics such as median error, the share within ±10%, hit rate and a calibrated confidence indicator. Our blog on how accurate is AI property valuation walks through those metrics and a blind back-test step by step.
The short version for decision-makers: ask for results by location, price tier and property type, ask how each metric is defined, and set the acceptable error before you test, based on what a wrong value costs.
See How Valuation AI Handles Review and Audit
Walk through comparable analysis, confidence insights, audit logs and configurable approvals.
How do you monitor AI property valuation accuracy after launch?
Track its error against new closed sales on a schedule, by market and property type, and retest when markets move or the model changes. A model that tested well last year can drift this year.
The IAAO standard offers a useful vocabulary for ongoing checks. Its ratio-study measures compare model values with actual sale prices:
| Measure | What it tells you |
|---|---|
Median ratio | Whether values run high or low overall |
Coefficient of dispersion (COD) | How tightly ratios cluster, a sign of uniformity |
Price-related differential (PRD) | Whether high-priced and low-priced homes are treated evenly; near 1.00 is the target |
Price-related bias (PRB) | Whether error rises or falls with value; the standard treats −0.05 to 0.05 as the acceptable band |
The standard also says to size training data sensibly, with at least five observations per independent variable and fifteen desirable, and to retest models on a holdout sample. These come from assessment practice, so lenders and brokerages should adapt them to their own use, but the discipline carries over: define the measures, run them on a schedule and keep the results.
A simple monitoring routine:
- Monthly or quarterly: compare model values with new closed sales.
- By segment: price tier, property type and neighborhood.
- After changes: new data source, model update or sharp market move.
- Escalation: a defined threshold that triggers a review of the model.
Can AI property valuation replace traditional residential property appraisals?
Not by default. An appraisal is performed by a licensed appraiser under appraisal standards. An AI value is an estimate, and whether it can stand in for an appraisal depends on the transaction, the institution and the rules that apply.
- Where AI values fit well: screening, portfolio monitoring, pricing support and refreshes between full valuations.
- Where rules allow a lighter valuation: federal banking agencies' 2019 rule raised the residential appraisal threshold to $400,000, with an evaluation required instead of an appraisal for transactions at or below it. Thresholds can change, so confirm the current figure.
- Where an appraisal is still needed: when a transaction requires one, or when a value will be challenged and needs the weight of a licensed opinion.
The Interagency Appraisal and Evaluation Guidelines, summarized in the Federal Reserve's supervisory letter, cover how institutions may use automated valuation models in evaluations. They also say a broker price opinion alone doesn't meet either standard. Automated residential property appraisal is therefore a loose phrase. An AI property appraisal or AI real estate appraisal tool still produces an estimate, and calling its output an appraisal in a report or marketing invites trouble, so call it an estimate or a valuation.
Who uses AI property valuation, and for what?
Valuation managers, heads of collateral and brokerage owners use it for different jobs, and the right review rules differ for each. Matching the use to the standard of evidence keeps the technology useful without overreaching.
| Role | Typical use | What they need from the value |
|---|---|---|
Valuation manager | Valuing large residential portfolios without ordering research property by property | Consistent method, reviewable evidence and exception routing |
Head of collateral | Monitoring collateral values and supporting lending decisions | Documented testing, controls and a record that stands up to audit |
Brokerage owner | Pricing support, listing conversations and screening | Fast, explainable estimates the agent can discuss with a client |
Notice what the three have in common: none of them wants a number alone. They want a number they can stand behind when someone asks "how did you get that?"
How can AI real estate valuation help professionals value properties faster and more consistently?
AI speeds up the research and makes the method repeatable, so two analysts valuing similar homes follow the same rules. Faster comes from automated data gathering and comparison. More consistent comes from fixed rules for choosing comparables and making adjustments.
Here's the consistency problem teams describe: "We need to value residential properties quickly for lending, acquisitions, or brokerage decisions, but different analysts often use different comparable properties and assumptions. How can AI create more consistent valuations while still allowing professionals to review the underlying data?"
Quick Answer: Standardize the method and keep the evidence open. The same comparable-selection rules apply to every property, adjustments are recorded, and reviewers can open the comparables, see the adjustments and override them with a note. Consistency comes from the rules; judgment still comes from people.
For AI-powered residential property valuation to scale, define who reviews what. A common split is automatic approval for high-confidence values in familiar markets, quick review for medium confidence and full review for low confidence or high stakes. The review triggers listed under unusual properties, above, are a good starting point.
How can an AI property valuation be validated and defended?
A defensible AI value comes with its method, data, evidence, confidence and review record attached. Three terms matter, and they are not interchangeable:
| Term | Question it answers |
|---|---|
Transparency | What kind of model is this, and what data does it use? |
Explainability | Why did it produce this value for this property? |
Auditability | Who did what, when, and with which version? |
Here's what valuation leaders need to be ready to answer: "I am considering using an AI valuation model, but I need to explain and defend the value it produces to clients, lenders, or internal stakeholders. What data, methodology, confidence measures, and audit information should an AI property valuation system provide?"
To answer in short: for each value, keep a valuation file with:
- Method: the model type and version, in plain language.
- Data: sources, dates and anything missing.
- Evidence: the comparables used, how they were adjusted and which were excluded.
- Confidence: a range and a reliability indicator, checked against closed sales.
- Review: who approved or changed the value, when and why.
- Testing: the latest back-test results for this market and property type.
The IAAO standard supports this practice: it says documentation should support the market analysis and the final value formula, and that models should be tested on holdout samples before use and after implementation. A value with that file behind it is easy to defend, and one without it is an opinion with a decimal point.
What do compliance rules mean for AI property valuation?
The main US rules come from federal quality control standards for AVMs, bank model-risk guidance, fair housing and lending law, and appraisal rules. Which ones apply depends on who you are and what the value is used for, so treat this as orientation and have counsel confirm.
| Framework | Applies to | What it asks |
|---|---|---|
AVM quality control standards (FHFA, OCC, Federal Reserve, FDIC, NCUA, CFPB) | Mortgage originators and secondary market issuers using AVMs for collateral valuation on a consumer's principal dwelling | Policies so AVMs give high-confidence estimates, are protected from data manipulation, avoid conflicts of interest, get random sample testing and comply with nondiscrimination laws |
Federal Reserve model risk guidance (SR 26-2) | Banks | Risk management scaled to a model's materiality, including vendor models; it replaced SR 11-7 on April 17, 2026 |
Fair Housing Act | Housing and housing-related transactions | |
Appraisal and evaluation rules | Regulated lenders | When an appraisal is required and when an evaluation, which can use an AVM, is acceptable |
When federal agencies finalized the AVM quality control rule, the Federal Register notice shows commenters asked for more prescriptive confidence-score and testing standards, and the agencies declined to adopt them. In practice, you decide how to meet the principles, and you need records to show it.
Two practical points follow. First, nondiscrimination means checking for patterns: compare value errors across neighborhoods and property groups, using the same closed-sales test set you use for accuracy. Second, a brokerage that isn't a covered institution may still face these expectations through its lender and client relationships.
What mistakes do teams make with AI property valuation?
Most problems come from process, not technology. Watch for these:
- Treating one accuracy number as the truth: a single national figure says little about your markets and property types.
- Skipping the closed-sales test: the only way to know how a tool performs on your portfolio is to try it on sales you already know.
- Letting every value pass automatically: without review rules, errors in thin-data areas reach clients and lenders.
- Forgetting the record: if you can't show the data and method behind a value later, you can't defend it.
- Ignoring drift: markets change, and a model needs checking on a schedule.
- Calling an estimate an appraisal: it misleads clients and may create regulatory trouble.
Fixing these costs little compared with defending a value you can't explain.
How do you set up AI property valuation in your workflow?
Start with one use case, set review rules in advance, test on closed sales and expand once the results hold. The order below keeps the decisions ahead of the technology:
- Pick the first use: portfolio monitoring, lending evaluations, pricing support or screening.
- Define the tolerance: the error you can accept for that decision.
- Set review rules: which values pass, get a quick review or need full review.
- Test on closed sales: blind, by market and property type.
- Define the record: what is stored for each value.
- Pilot in one market or portfolio, then expand.
- Monitor: track performance, drift and exceptions over time.
What should you evaluate when choosing AI property valuation software?
When comparing AI property valuation software, evaluate accuracy evidence, transparency, compliance support and human review, and test them on your own data. Here's the worry behind most purchase decisions: "We want to reduce the cost and turnaround time of residential property valuations, but we cannot rely on a black-box model that creates values we cannot explain. What should we evaluate when choosing an AI property valuation solution for accuracy, transparency, compliance, and human review?"
For all those who wonder about this, use this checklist.
| Area | Ask | Warning sign |
|---|---|---|
Accuracy | Can I see back-test results for markets like mine? | Only one national figure |
Method | Which approaches are used, in plain terms? | "Proprietary AI" and nothing more |
Data | Which sources, how fresh, how are gaps handled? | Sources unnamed |
Explainability | Can a reviewer see the comparables and adjustments? | A single number |
Confidence | How is it calculated and was it checked against sales? | An unexplained score |
Audit | Are values, changes and reviewers logged? | No history |
Compliance | What support exists for QC testing and bias checks? | A label with no detail |
Review workflow | Can I set my own thresholds and approvals? | Fixed rules |
Integration and security | How does it connect, and how is data protected? | No detail |
Pilot | Can I test it on my own closed sales? | Demo only |
Valuation AI describes comparable property analysis, confidence insights that flag data gaps and valuation variance, audit logs, configurable review and approval workflows, integrations with MLS and property databases and valuation reports. Its page doesn't publish accuracy results, the model methods used or how confidence is quantified, so ask for those in a pilot, as you would with any vendor.
Put an AI Valuation Tool to the Closed-Sales Test
Bring sales you already know and see how a tool's evidence, ranges and review trail hold up.
Ready to Make Your Valuations Hold Up Under Questions?
A valuation you can't explain is a lot like a magic trick: impressive until someone asks to see the sleeve. Ask for the method, the data and the evidence, test on closed sales, set your review rules before you scale and keep the record. Want a second set of eyes on how that would work in your workflow? Reach out to the Svermo team.
 https://www.linkedin.com/in/saanvi-verma-38711a36a
FAQs
An AVM is the model that produces a value estimate. AI property valuation is the broader idea of using AI and statistical models, often including AVMs, plus the data and review process around them.
No. An appraisal is performed by a licensed appraiser. An AI tool produces an estimate, which may be acceptable for some uses and not for others.
Property records, sales history, listings, location and market data, and condition information when available. Complete, current, verified data matters more than volume.
Yes, for pricing support and screening, with clear review rules. Describe the output as an estimate and keep the evidence with it.
No. Typical, well-documented homes in active markets suit it best. Unusual, rural or rapidly changing properties should trigger lower confidence and human review.
It is the use of algorithms that learn price patterns from many past sales. It can capture complex relationships, but it can be harder to explain than a comparable-based approach, so ask how a tool shows its reasoning.
The value and range, the comparables and adjustments, data sources and gaps, a confidence indicator and the review history.
On launch, after major changes and on a regular schedule, especially when markets move fast. Track results by market and property type.